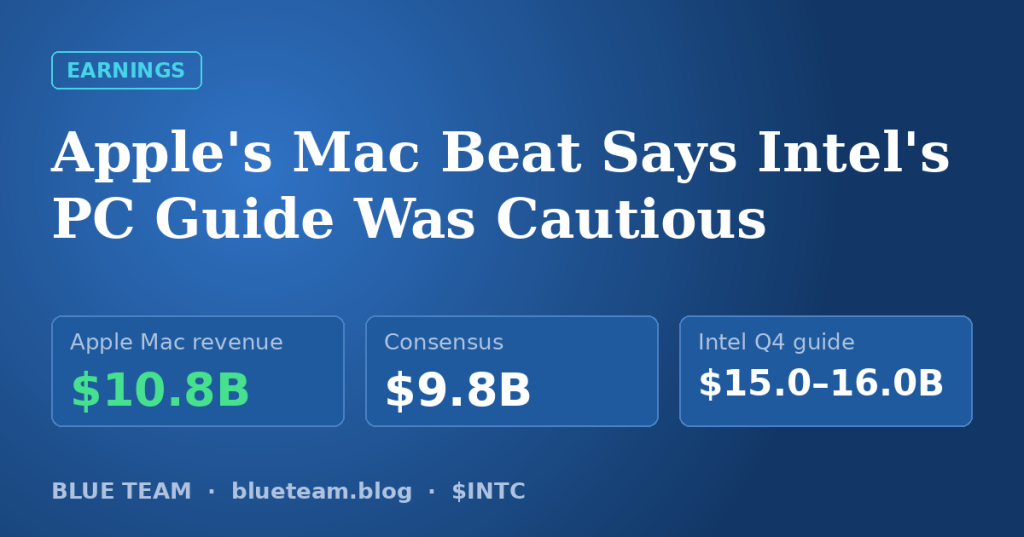
Apple reported its September quarter tonight and nearly every line came in ahead of expectations. Revenue was a record $114.5 billion against a consensus near $113.4 billion. EPS was $2.10 against $1.98. iPhone was $57.6 billion against $56.6 billion.
For Intel holders, one number matters more than the rest: Mac revenue of $10.8 billion, against a FactSet consensus of $9.8 billion. That is roughly a quarter higher than a year ago.
Same memory crunch, very different message
Three days earlier, Intel guided fourth-quarter revenue to $15.0 billion to $16.0 billion, a midpoint of $15.5 billion and a step down from Q3’s $16.5 billion. Much of the caution was about PCs. CFO David Zinsner said Intel expects the 2026 PC unit market to fall about 12%, with second-half units down more than 20%, and that a sustained recovery should not be expected until memory availability improves.
Apple faced the same memory prices and the same tight supply of leading-edge chips, and still beat on Mac by about $1 billion. People are buying computers when the product is on the shelf.
Intel’s own call pointed the same way. Lip-Bu Tan said demand for Wildcat Lake “is outstripping supply” and that Nova Lake, Intel’s first 18A-P client chip, “is tracking ahead of schedule.”
A guide of $15.5 to $16.5 billion was within reach
Our view: Intel could have guided $15.5 billion to $16.5 billion. That is only half a billion above the midpoint it gave, it would have kept revenue roughly flat with Q3, and the market would have digested it far more easily than the 30% one-day drop it got.
Intel chose the low road for understandable reasons: the Israel factory shutdown hits Q4 directly, and server demand is capped by wafer and substrate supply, not by customers. But this management team has a habit. Zinsner called Q3 “the eighth consecutive quarter of exceeding our financial expectations.”
If that habit holds, Q4 lands around $16 billion or better, and January’s report becomes a relief rather than a test.
What the Apple beat does not say
Mac runs on Apple’s own chips, built by TSMC. Part of Mac’s growth comes from schools and companies replacing Windows machines, so this is not a direct sale for Intel. And revenue was not the only reason INTC fell: the 38% gross margin guide, down from 44.1% in Q3, and $0.25 of EPS did more damage than the revenue range.
What it does say is that the PC market Intel described as falling hard is still paying up for good machines. That is the market Panther Lake, Wildcat Lake and Nova Lake are aimed at once supply catches up.
Apple’s call with investors follows tonight. We will update if anything on chips, supply or US manufacturing comes up.
Sources: Apple fourth quarter fiscal 2026 press release, November 2, 2026; FactSet consensus via MT Newswires; Intel Q3 2026 earnings release and call, October 29, 2026. Not investment advice.


Leave a Reply